MAGNITUDE

Climb.

For anyone whose ambition is ahead of their income.

On purpose.

You don't lose to the past, you win the future.

Systems.

Run your household finances like a company does.

Income

It gives your money a purpose before you spend it.

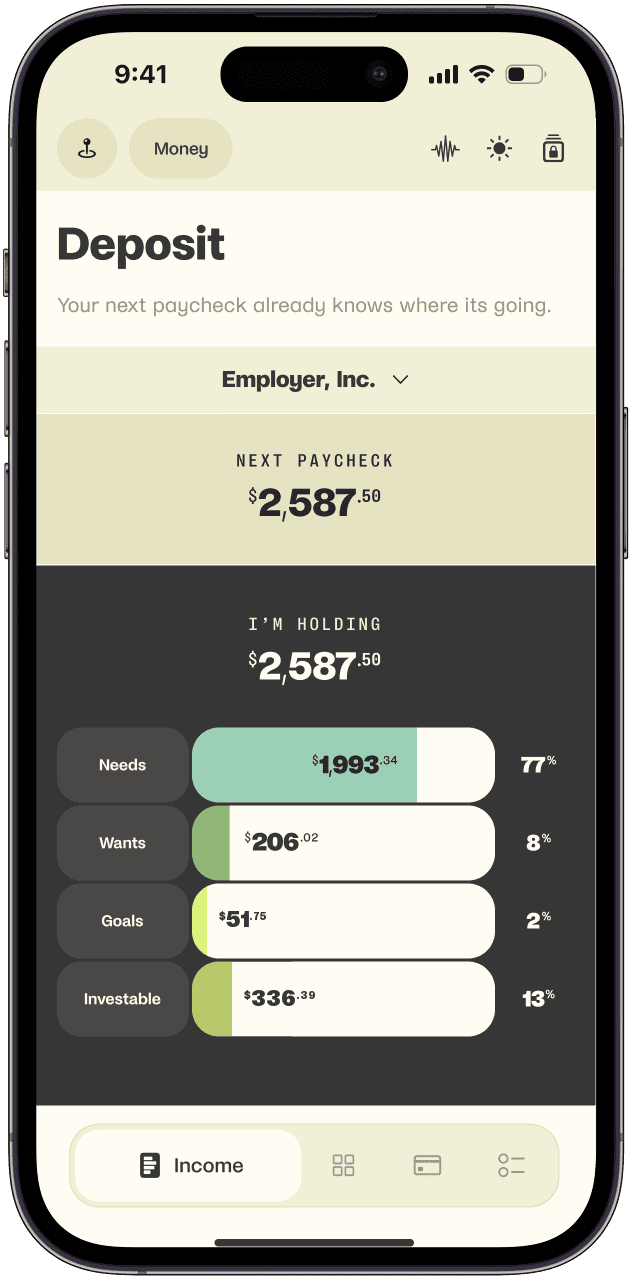
Magnitude divides your income across needs, wants, goals, and investments¹.

¹ Transfer investments into a Vanguard index fund (e.g., VTI, VOO) at your brokerage.
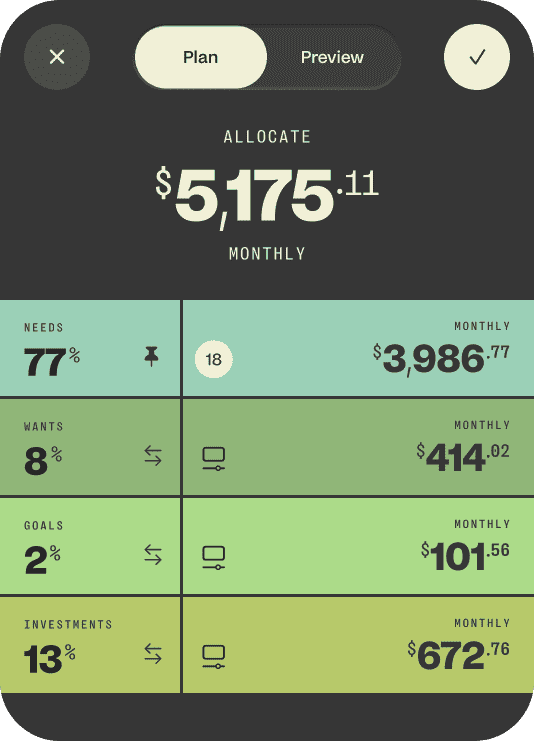
Allocation screen showing income split across needs, wants, goals, and investments
Expenses

It starts with what people near you actually spend.

Each balance begins at a benchmark² and adapts to you.

² From the Bureau of Labor Statistics.
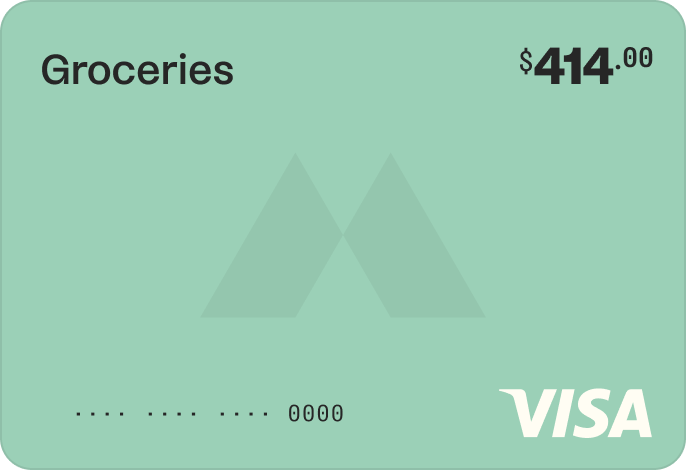
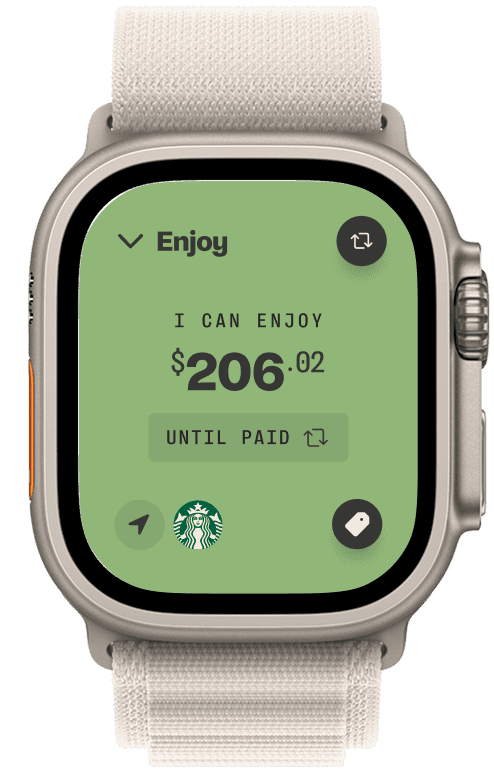
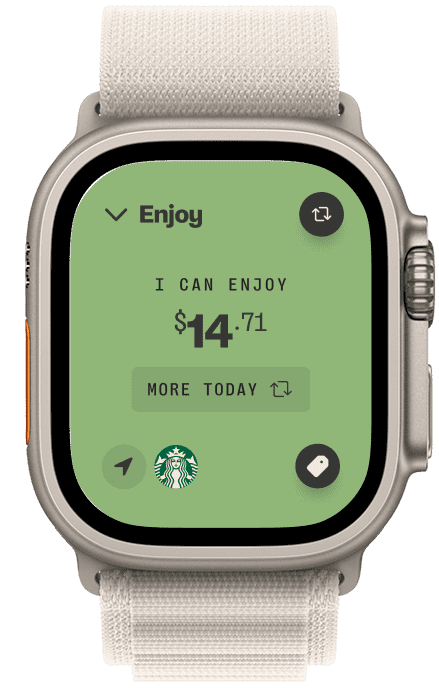
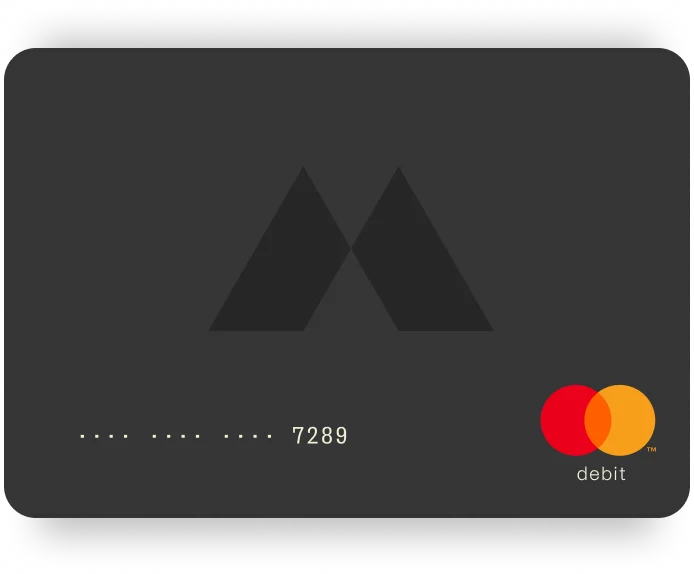
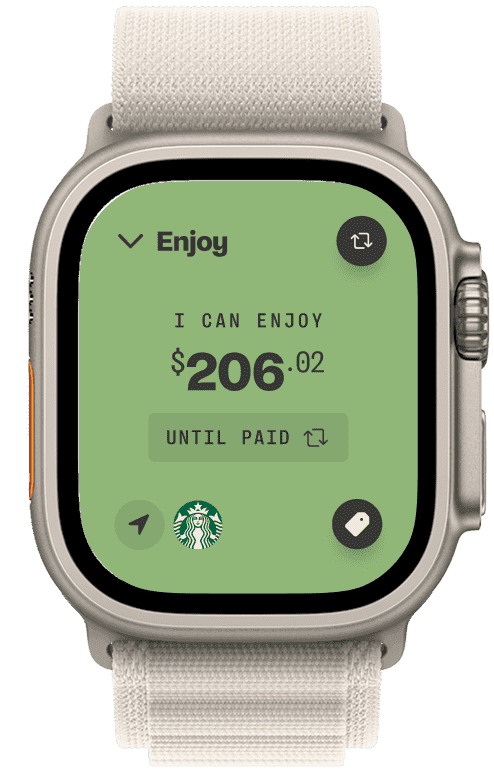
Magnitude debit cardMagnitude watch app
Checkout

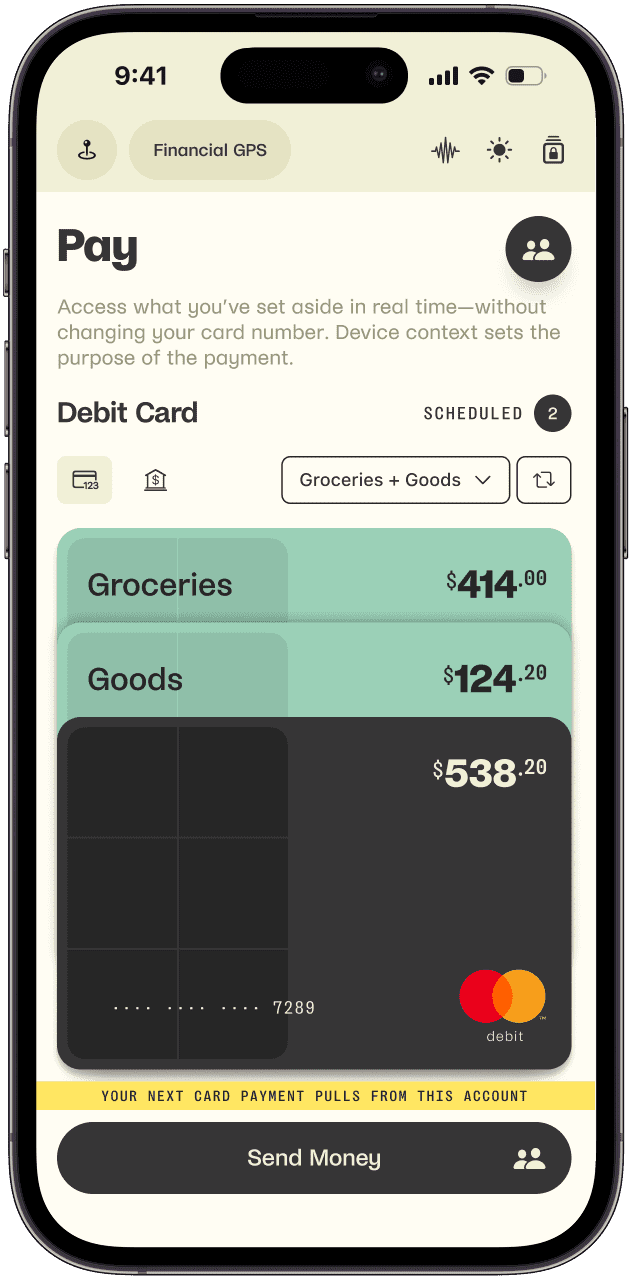
It pays from the right balance the moment you tap.

In stores and online, your card knows³ which part of your plan a purchase belongs to.

³ Works on iPhone and Apple Watch. Location is optional.

Blog

The Ascent.

How ambition becomes altitude.

Direct

Answers.

  • What is Magnitude?
    Magnitude makes preallocation possible the moment money arrives, then binds it to the right balance before it leaves. Your needs, your wants, and your goals each keep their own money, so there's nothing to track and nothing to hold in your head.
  • How does it work?
    Rather than putting the money you make into one balance, or transferring it between several, Magnitude partitions your take-home into two: Necessary and Discretionary. 70/30 to start, until it learns yours. Necessary fills first. It partitions again across your recurring expenses, starting from localized benchmarks that adapt to your income and your actual costs. Discretionary — the remaining 30 — splits evenly across wants, goals, and investable. 10/10/10 by default, and yours to change. Wants partitions once more into a spendable per diem that runs until your next paycheck lands. Goals are what you'd like to fund in the near future. Investable sets money aside each month for you to route to your brokerage, IRA, or 401(k). Every purpose-bound balance is governed by time, and time is the constant that makes everything in Magnitude measurable. You stop holding it in your head, working it out on your own, or wondering what comes next. You can see exactly where you stand and how high you can climb. If you've already built your nest egg, Magnitude shows you what it takes to make it last. And once you've built real wealth, you can make it generational.
  • Who is it for?
    For anyone whose ambition is ahead of their income, and who knows what this feels like: The number in my account has never been the number I can spend. I do the math in my head every time I look. At least half of my paycheck goes to the past, to things I put on my credit card, and I carry a balance because I don't want to part with all my cash. I've tried budgeting tools, but they're perfect plans that never end the way they begin, so I don't even like to look anymore. It shouldn't be this hard. I don't need another net worth number. I want to enter one number, what I make in a year before tax, and watch the whole thing work. Everything after that should figure itself out, or change with a tap. I want to see what my life costs, what's mine to enjoy, which goals I'm funding, and how much I can invest, so I know how close I am to real wealth. And I don't want another monthly or annual subscription. I want to pay once. One and done. Do that, and I'm yours. That's what we built.
  • How is it different?
    Traditional banks give you one number for everything. Everything comes in. Anything goes out. Nothing stops it. Neobanks swap the branch for a better app, but it's still one number for everything. Credit cards take advantage of how that number swings. Paying one card is easier than paying 20 bills, but now most of your next paycheck goes to last month. Nobody can hold that in their head, so what do we do? We turn to budgeting tools, a brittle connection to your bank and card balances. The connection often breaks, and even when it holds, the tool can't enforce the plan you made. That's why so many people stop using them. Magnitude works before the number, not after it. The moment your paycheck lands, it's divided across needs, wants, goals, and investments, each with its own balance. Money for what's coming is set aside first, so it isn't competing with last month's bill. And you can leave your budgeting subscription behind, because there's nothing left to track. The difference is simple: Every tool tracks your transaction trail. Magnitude puts your paycheck on a path.
  • What does it cost?
    Every plan is paid once. No renewal, no monthly fee, nothing billed again. Ultralight, $24. Your whole plan, built for you, not by you, so you can see it before you move your direct deposit. Ultra, $149. Everything in Ultralight, plus banking, routing, and the card that pays from the right balance. Ultra Unified, $199. Everything in Ultra, for two: joint banking, both paychecks preallocated, shared bills forecast, and private spending for each of you. Ultra and Ultra Unified are on pre-order now, fully refundable until launch. Upgrade anytime, and what you've already paid counts in full.
  • What's the difference between Ultra and Ultralight?
    Ultra. Your paycheck comes here. The plan does the work: income lands, splits across your reserves, and the right one pays at the register — your location, if you choose to share it, helps it know which one. You decide once; nothing after that is yours to do. $149 once, fully refundable until launch. Ultralight. The same plan, built the same way. Magnitude fills in the numbers and shows you where your money should go, so you can see it all before you move your direct deposit. $24, once.
  • What's Ultra Unified?
    $199, once. Ultra Unified is Ultra for two. Both paychecks are preallocated into one plan, shared bills come from a joint account, and each of you keeps private spending of your own. One system underneath both of you.
  • What does it look like when I sign up?
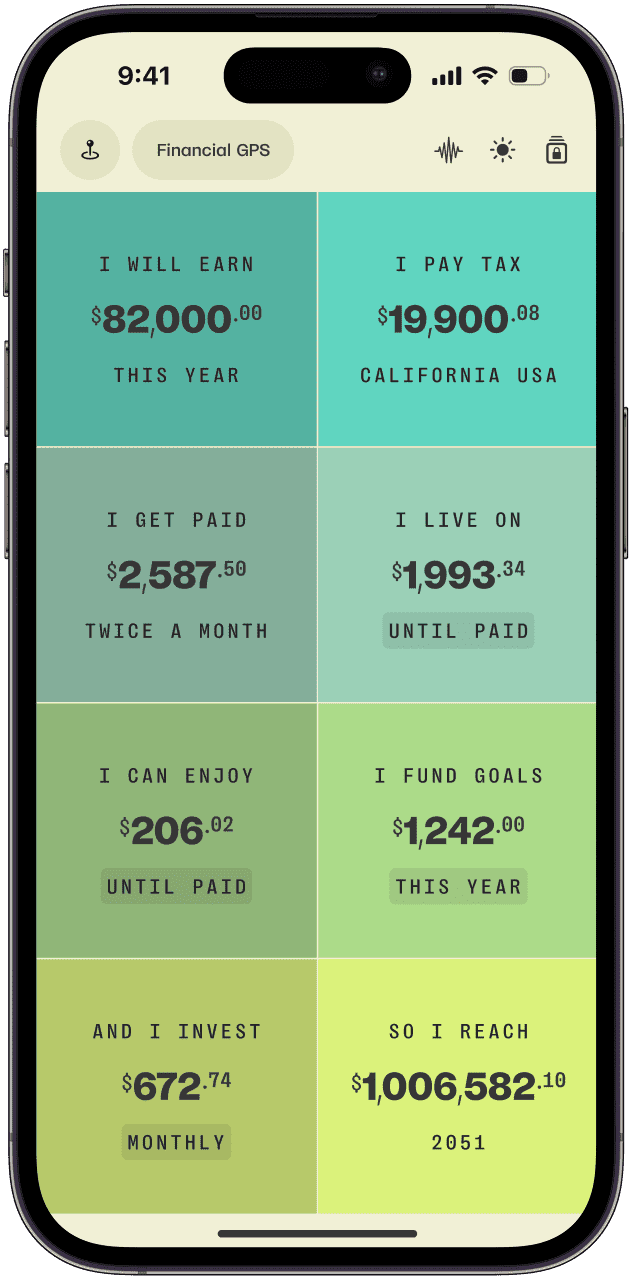
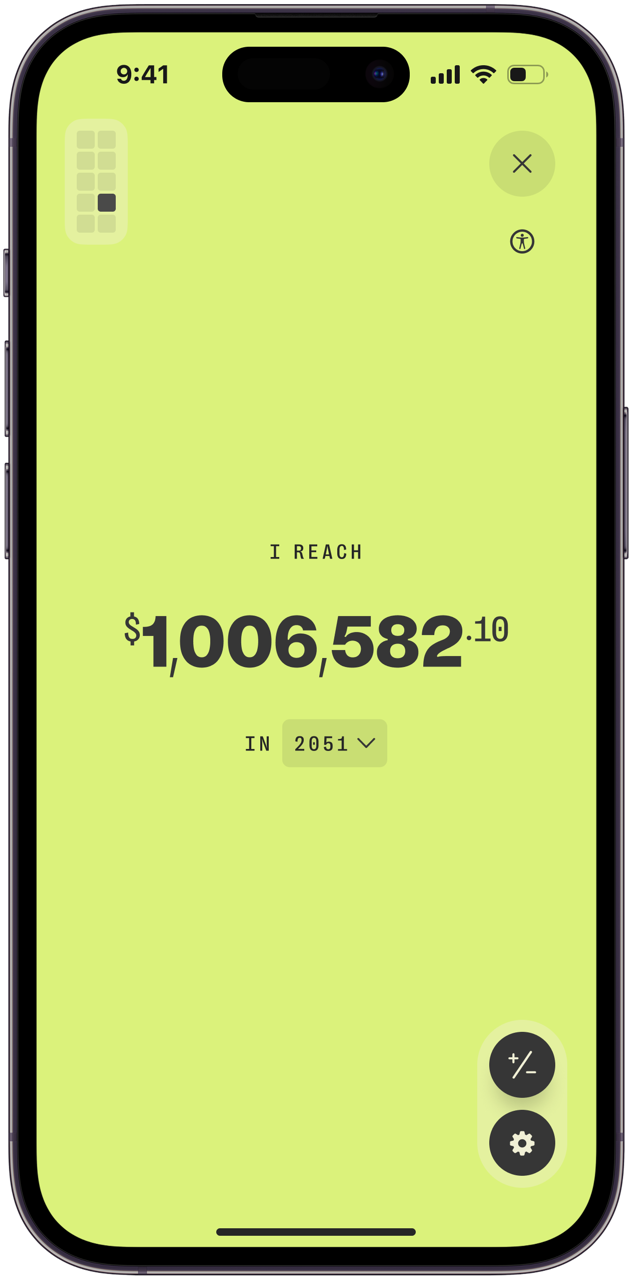
    You enter one number: what you make in a year, before tax. That's the whole setup. Every money app is built around the money. Magnitude is built around you. You come first, the number comes second. So here's what that one number turns into. You see what you actually take home. You see what your life costs. You see what's yours to enjoy. You see which goals you're funding. You see how much you can invest, and how close that puts you to real wealth. One income, doing all of it at once. You just couldn't see it before.
  • What happens when my paycheck lands in Magnitude?
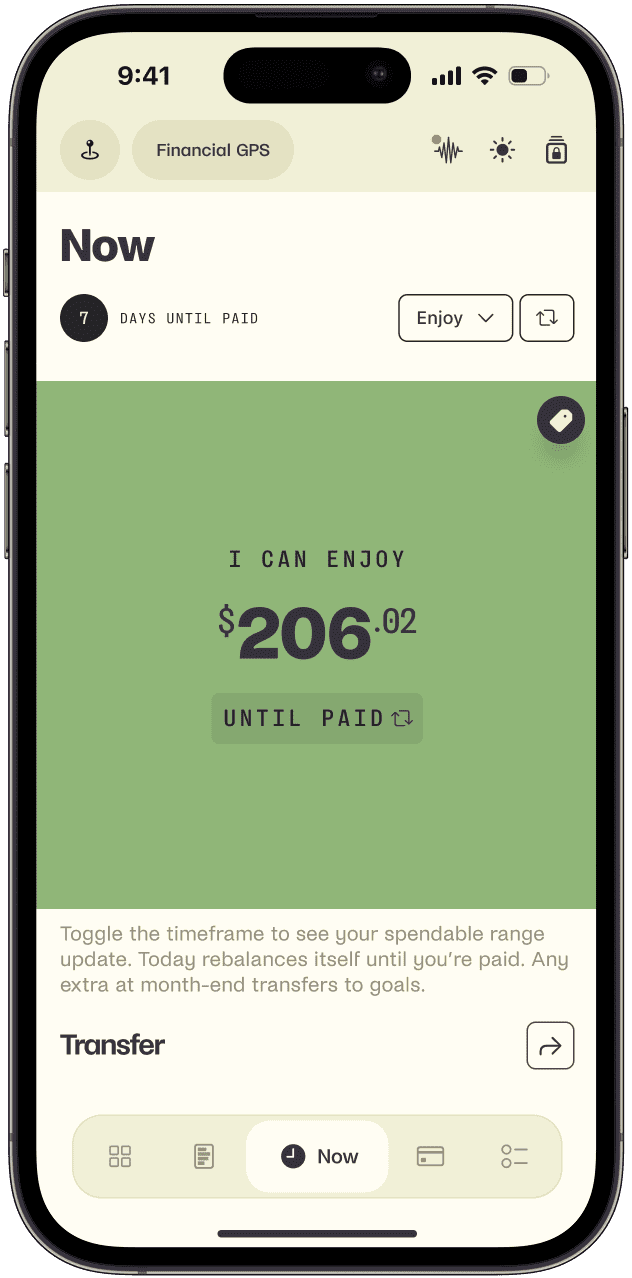
    This is the moment Magnitude was built for. Income lands and routes itself, in the order you set. Needs first: housing, utilities, the things that must be paid on time, every time. Then what's yours to enjoy, the goals you're funding, and what you'll invest. You make the big decisions once, not a hundred times a month. Everything after is follow-through. That's the payday feeling. Every time you open Magnitude.
  • What happens when I pay for something?
    You tap your Magnitude debit card and the money comes from the right place on its own. Groceries pull from groceries. A night out pulls from wants. Your rent or mortgage stays where it belongs. It looks like one debit card. Behind it, every part of your life is kept separate, so a swipe today can't quietly rob what's already spoken for. Your whole life, one number has made everything fight for the same pile. First swipe wins. Magnitude ends that, and there's nothing to categorize afterward, because you already decided.
  • How does Magnitude make money?
    A one-time fee can't run a service forever, and we don't pretend it does. What you pay once builds it and sets you up. After that, we're paid through interchange, a small fee the merchant's bank pays each time you use your Magnitude debit card, which our card program shares with us. It costs you nothing. That's the alignment. We earn when you spend money you'd already set aside, not when you're confused, overdrawn, or in debt. In Magnitude, you can't overdraft, and we'll never ask for a tip. We can't earn by pushing you past what you have, because you can only spend what's there. We only win when you win, which is rarer in finance than it should be.
  • Do I have to get my plan right on day one?
    No. You can change your plan before or after your money lands, because it's made to move with you. First, Magnitude fills in the numbers with what people near you actually spend on groceries, gas, and utilities, so you start from benchmarks that work instead of a replay of last month. From there, everything bends to you and nothing breaks. Move money, adjust a split, undo any of it. Anytime. Every financial plan sounds perfect until it meets real life. This one starts strong and sharpens itself with each swipe.
  • What if I lean on credit cards today?
    Plenty of people use credit and always will. Nothing here asks you to stop. But plenty of people choose debit instead, to keep every purchase tied to money they actually have. Two, three, even four percent back sounds like free money. Then set it against what credit actually costs: people spend more when they don't see the money disappear right away, and about half of cardholders carry a balance at an average rate north of 20%. A few percent doesn't survive either one, let alone both. Magnitude is built for that decision. What you need is funded before it's due, what's left to enjoy is genuinely yours, and you stop needing next month's money to cover this one.
  • What if money's tight, I overspend, or something goes wrong?
    Magnitude works at any income level. When money is tight, it matters more than ever. The more you make, the more room you have to maneuver. Either way, it's the order that does the work. Essentials are funded first. Everything else waits its turn. You'll know before you're in the aisle. If you share your location, walk into a grocery store and your phone tells you what's actually there: $400 available, enough for two $200 trips before your next paycheck. If something still runs short, it stays small and it stays visible. Magnitude covers it from your buffer, or asks where you'd rather make the trade, never quietly, and never by pushing you into hidden debt. And emergencies don't have to blindside you. Set one up before you need it and fund it a little at a time. Problems surface early, while they're still small enough to fix.
  • Is my money safe?
    Magnitude is a financial technology company, not a bank. Your funds will be held at our partner bank (Member FDIC), whose name we'll disclose at launch. FDIC insurance covers up to $250,000 per depositor, per insured bank — and it protects against the bank's failure, not Magnitude's. That limit applies across everything you hold with us — it doesn't multiply because your money is split into separate balances.
  • Is my financial data private?
    Yes. We don't sell it, we don't share it with advertisers, and we don't hand it to data brokers. There's no asterisk on any of those. Some parties see it because they have to: the bank that holds your money, the card network that moves it, and whatever the law requires every financial institution to report. When we add an outside service, we'll tell you. Most of what you ask Magnitude runs on your phone. If a question needs more context than the device holds, it goes to a cloud model — your name doesn't go with it, and neither does raw audio. If you spoke it, what leaves is text. What we do is keep it — all of it, indefinitely. That's deliberate. Your trajectory is the product, and how far you've come only means something with years behind it. Data we deleted is a picture we can't show you. Turn on location and Magnitude tells you what's available before you're in the aisle. That's the trade: your phone says you're at the store, and that becomes part of the record. Switch it off whenever you want.
  • Do I have to switch banks and move my direct deposit?
    Yes. Your paycheck comes here — the routing can't work on money it never receives. The switch itself is one form. When we launch, we'll walk you through opening your account with our partner bank, then hand you step-by-step instructions or a pre-filled form for your employer. And keep your old account open. We'd rather you did. Give this one month, watch where your money goes, and you'll never go back.
  • How do I cancel my account?
    Magnitude isn't for everybody. If it turns out not to be for you, you move your money out — no hoops, no retention offers. Closing your bank account doesn't cancel Magnitude. You paid once and it stays yours: the plan you built, the picture of where your money goes, all of it. Come back in a year and it's exactly where you left it. Before launch, your $149 comes back in full. After launch it doesn't, because you keep what you paid for. The app will soon let you delete everything yourself — no email, no permission needed. Close your bank account first, though: deleting your data doesn't close it. We keep certain banking records for five years because the law requires it, and after that those go too. If something went wrong, tell us before you go. We'd rather fix it.
  • Can I take my data with me if I go?
    Yes. We'll give you a spreadsheet of everything you've entered and a full transaction log — before you go or after. Not all of it will map neatly onto other personal finance tools. Magnitude is structurally different from the rest, and the export reflects that.